Remodeling your home is one of the most exciting improvements you can make. It’s also a major investment. And if there’s one detail I’ve seen San Diego homeowners overlook time and again, it’s insurance.
Whether you’re adding an ADU, reworking your layout, or upgrading finishes, your remodel affects more than just style, it impacts your home’s value and your liability. With wildfire risks, coastal flooding, and San Diego’s strict permitting process in the mix,1 insurance should be part of your planning from the very beginning.
In this guide, I’ll walk you through the key coverage steps at every stage, so you can protect your investment and move forward with confidence.
Prefer to listen instead? Check out the podcast version of this guide. Perfect for tuning in while you plan your remodel. 👇
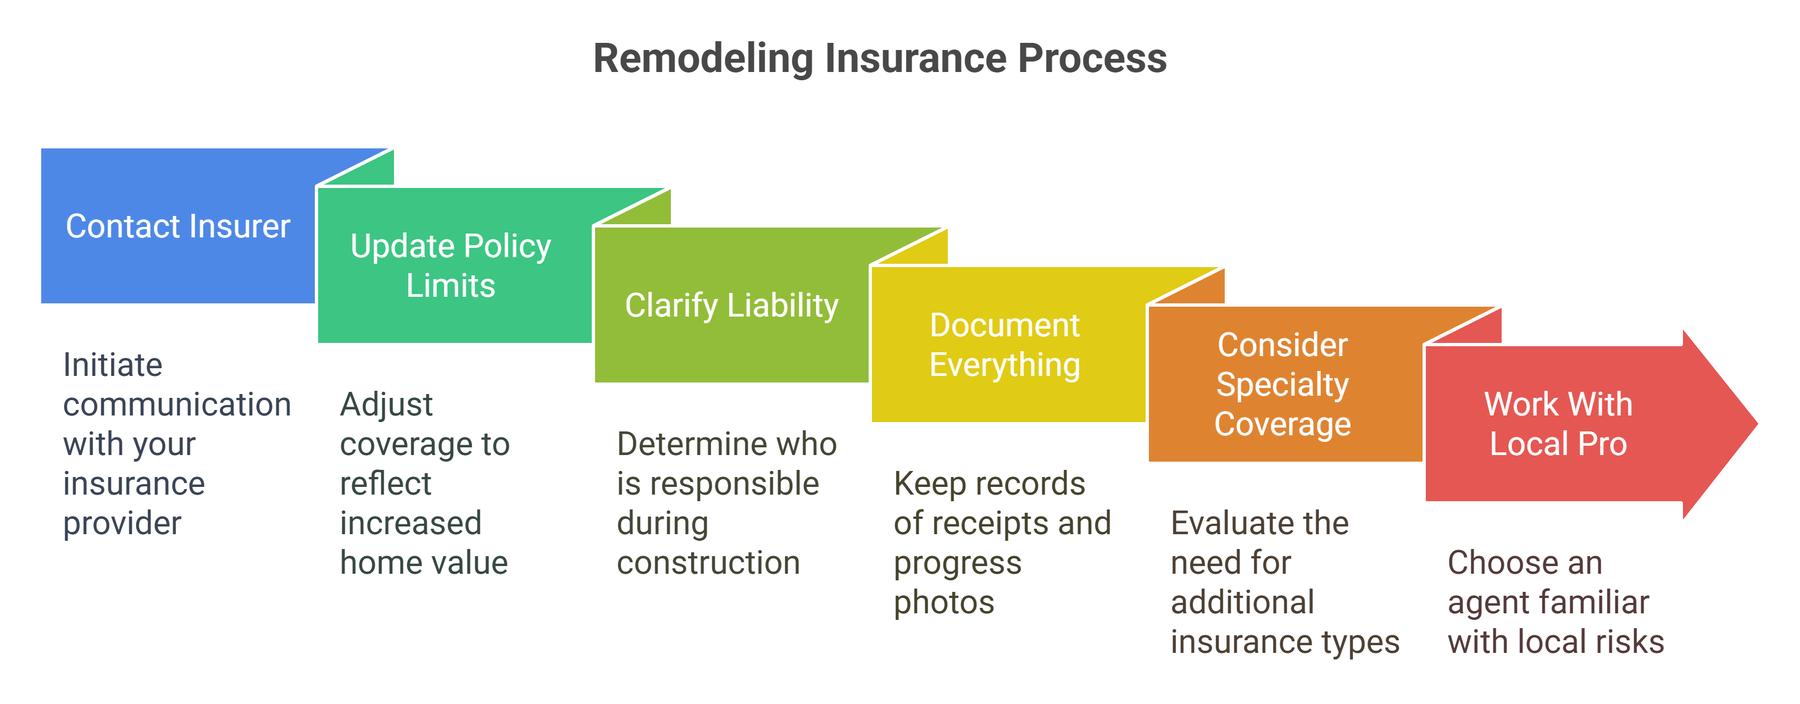
Insurance Requirements Disclaimer
Important Note: Insurance requirements and coverage options can change frequently based on market conditions, regulatory updates, and carrier policies. While this guide provides general best practices for San Diego homeowners, always verify current requirements and available coverage options directly with your insurance provider or a licensed agent before making any decisions about your remodeling project.
Pre-Remodel Insurance Essentials
Review Your Current Homeowners Policy
Before you start picking out paint colors, call your insurance provider. A remodel can significantly alter the value of your home, and your current policy may not reflect those changes. Policy limits, exclusions, and terms need to be revisited.
Make sure your policy covers:
- Structural changes
- Temporary displacement
- Damage during construction
| Key Factor | What to Review | San Diego Homeowner Tip |
|---|---|---|
| Structural Changes | Make sure your policy includes coverage for load-bearing wall adjustments, additions, or new layouts. | If you’re adding a second story or ADU, confirm with your insurer that those changes won’t trigger policy exclusions. |
| Temporary Displacement | Look for “Loss of Use” or “Additional Living Expense (ALE)” provisions in your current policy. | Ask how much daily coverage is provided if you have to relocate during construction, especially relevant for full remodels in San Diego’s permitting zones. |
| Construction-Related Damage | Check if your policy includes protection for damage caused by tools, tradespeople, or accidents during work. | Storms and coastal weather can hit mid-project. Ensure accidental damage during remodels is covered. |
Understand Policy Exclusions and Gaps
Some homeowners are surprised to find their policies exclude damage during renovations, especially if the property is deemed “vacant” or “unoccupied.” This is especially common in major remodels where you’re living off-site.
| Exclusion or Risk | What to Ask or Do | San Diego Homeowner Tip |
|---|---|---|
| Vacant or Unoccupied Home | Ask your insurer if vacancy exclusions apply during extended remodels. | If you’re living off-site during construction, request a “vacancy permit” or endorsement to avoid denied claims. |
| Fire, Theft, or Vandalism Gaps | Check if damage from these risks is excluded during renovations. | Homes near canyons or high-risk fire zones, like Rancho Santa Fe, may need additional endorsements for wildfire or theft protection. |
| Policy Endorsements or Riders | Ask your agent about riders for remodel coverage or temporary risk increases. | A builder’s risk endorsement might cost less than a separate policy, especially for smaller projects in Del Cerro or Clairemont. |
What Homeowners Should Know: An unoccupied home under renovation may not be covered for fire, vandalism, or theft. Talk to your insurer about an endorsement or temporary coverage. Ask if your provider offers a “vacancy permit” or rider to bridge the gap.
Get an Updated Appraisal or Valuation
Home improvements, such as adding new square footage or installing luxury finishes, can impact your replacement costs. An updated home appraisal helps your insurance agent set accurate policy limits to match your remodel’s new value. It’s also essential for refinancing and resale down the road.
| Appraisal Factor | What to Do | San Diego Homeowner Tip |
|---|---|---|
| Square Footage Increases | Order a professional appraisal once additions are completed. | ADUs and room additions in areas like North Park or Encinitas can greatly boost your rebuild value and property taxes. |
| Luxury Finishes or Custom Work | Update your policy with accurate material and labor values. | Custom tile, imported stone, or smart home tech need to be factored in for accurate replacement cost estimates. |
| Refinancing or Resale Planning | Use your updated valuation to adjust insurance, taxes, and mortgage terms. | A post-remodel appraisal in La Jolla or Carmel Valley could unlock favorable refinance rates or boost resale value significantly. |
Consider Increased Personal Property Coverage
If you’re adding new appliances, furniture, or electronics during the remodel, it’s smart to increase your personal property limits. Standard policies may not automatically cover high-value upgrades, such as a smart appliance suite or a built-in home theater system.
| Item Category | Why It Matters | San Diego Homeowner Tip |
|---|---|---|
| Smart Appliances | These often exceed standard policy coverage limits and may require endorsements. | Document model numbers and installation dates, especially for integrated smart kitchens in high-tech communities like Del Mar Heights. |
| Built-in Systems | Custom AV setups or home theater systems are costly to replace and must be fully listed. | Include receipts and installation diagrams in your insurance binder to simplify future claims. |
| Furniture & Decor | High-end furniture or designer pieces may exceed policy sub-limits. | Schedule an inventory update after your remodel, especially if you’re furnishing upgraded living spaces in luxury areas like Coronado or Rancho Santa Fe. |
Talk with Your Remodeling Contractor
At Kaminskiy, we provide every client with detailed plans and permit records. These can be shared with your insurance agent to ensure proper coverage during the remodel. A design-build firm like ours helps streamline this process.
I always encourage clients to bring their remodel plans to their insurance agent early. It’s one of the easiest ways to prevent costly gaps in coverage.
| Documentation Type | Why It’s Important | San Diego Homeowner Tip |
|---|---|---|
| Remodel Plans | Gives your insurer a clear view of the scope, value, and risk of the project. | Bring these to your insurance agent before demo day, especially for major additions or structural changes. |
| Permit Records | Proof that all work is city-approved and compliant with building codes. | San Diego’s permitting can be strict. Use these documents to show code compliance if you ever need to file a claim. |
| Contractor Credentials | Ensures your builder is licensed and insured, protecting you from liability. | Kaminskiy clients receive this upfront, share it with your insurer early to smooth the policy update process. |
Contractor Insurance and Documentation
Confirm Contractor’s General Liability Insurance
Verify that your contractor has up-to-date general liability coverage. This protects you if they cause accidental damage to your home or if third-party injuries occur during the project.
Workers’ Compensation Insurance
Ensure your contractor carries workers’ compensation insurance for their employees. Without it, you could be financially responsible if someone gets injured while working in your home.
Request Proof of Insurance
Ask for Certificates of Insurance (COI) and keep them on file. This includes:
- General liability
- Workers’ compensation
- Builder’s risk (if applicable)
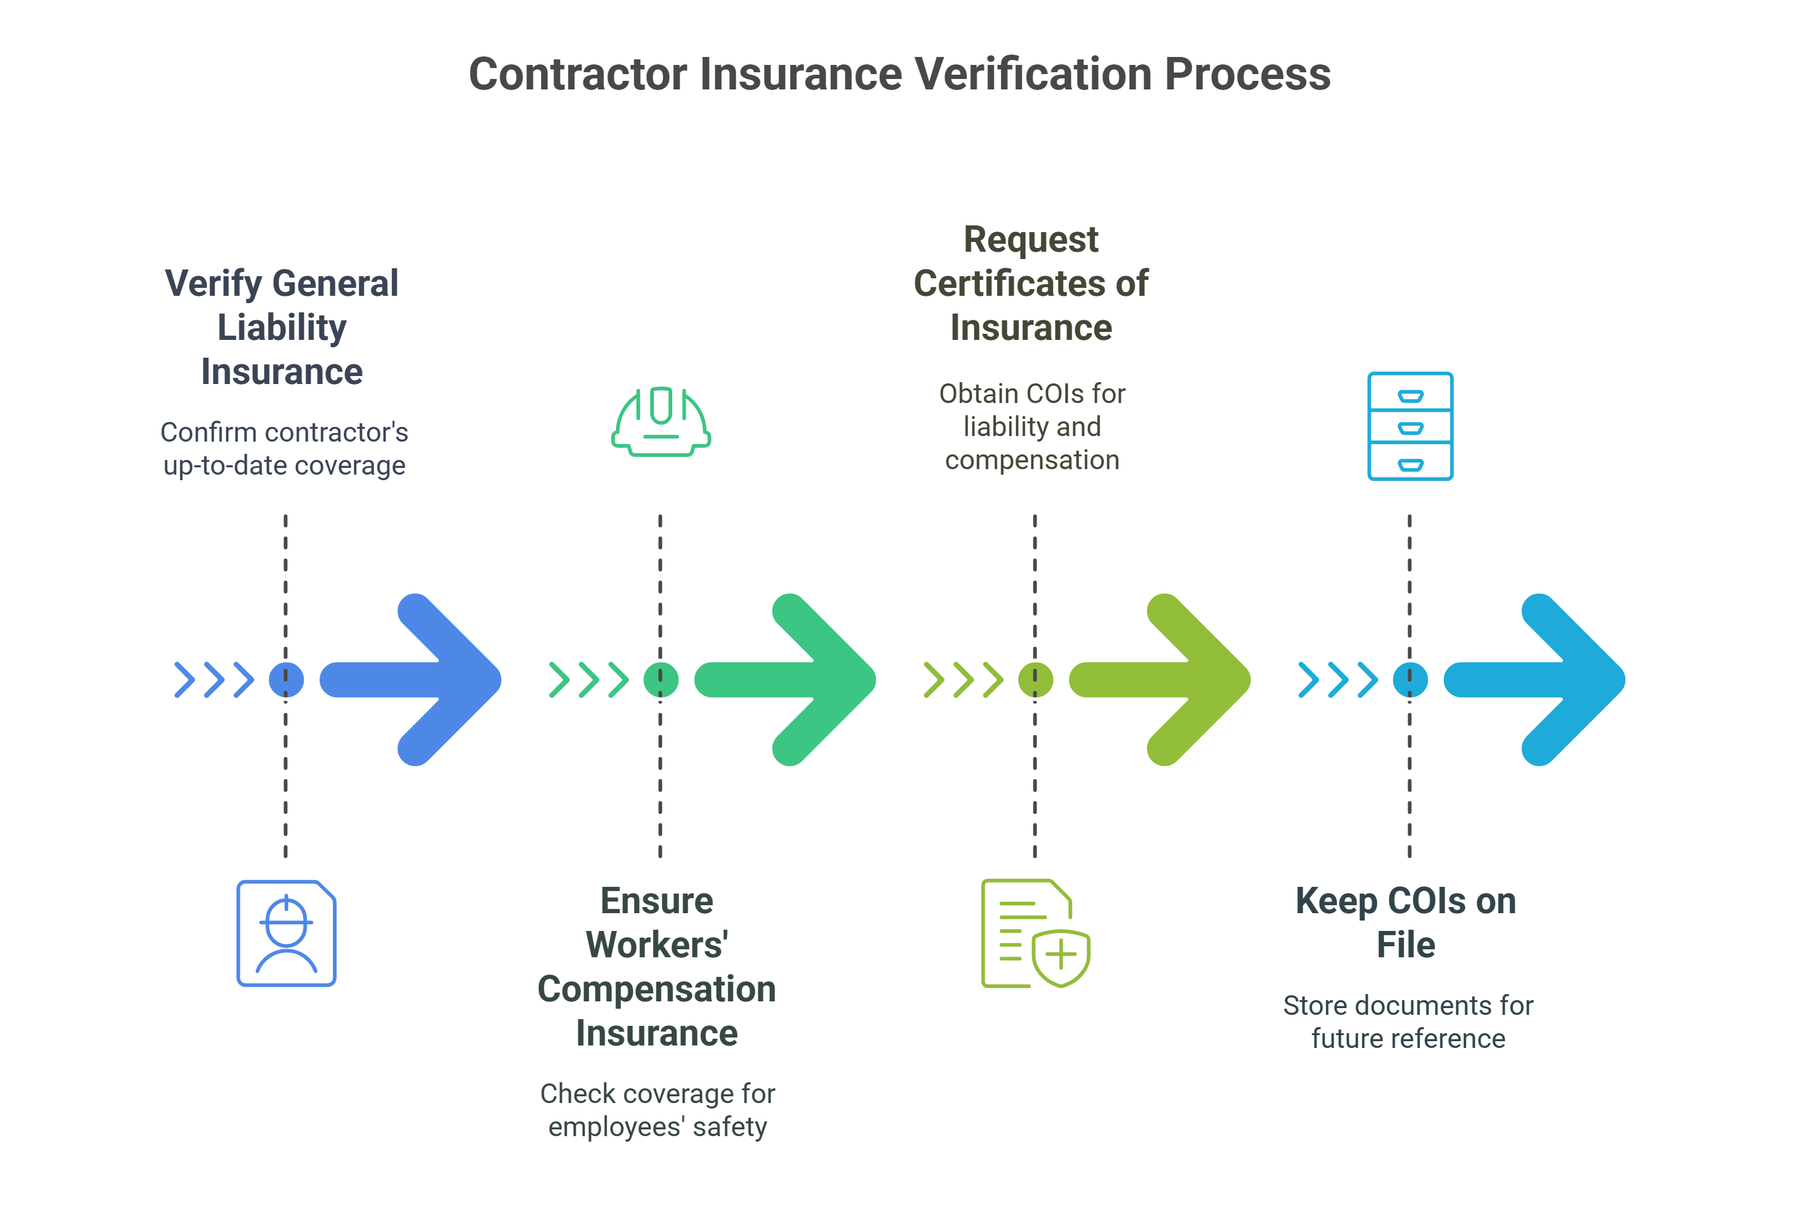
Insurance You’ll Need During Construction
Builder’s Risk Insurance: Protection and Scope
Also known as Course of Construction Insurance, this coverage protects the structure and materials during the remodeling process. It protects against theft, vandalism, fire, and weather-related events.
What It Covers:
- Building materials onsite or in transit
- Temporary structures
- Damage due to fire, wind, theft, or vandalism
- Some policies also include materials stored off-site and on-site equipment
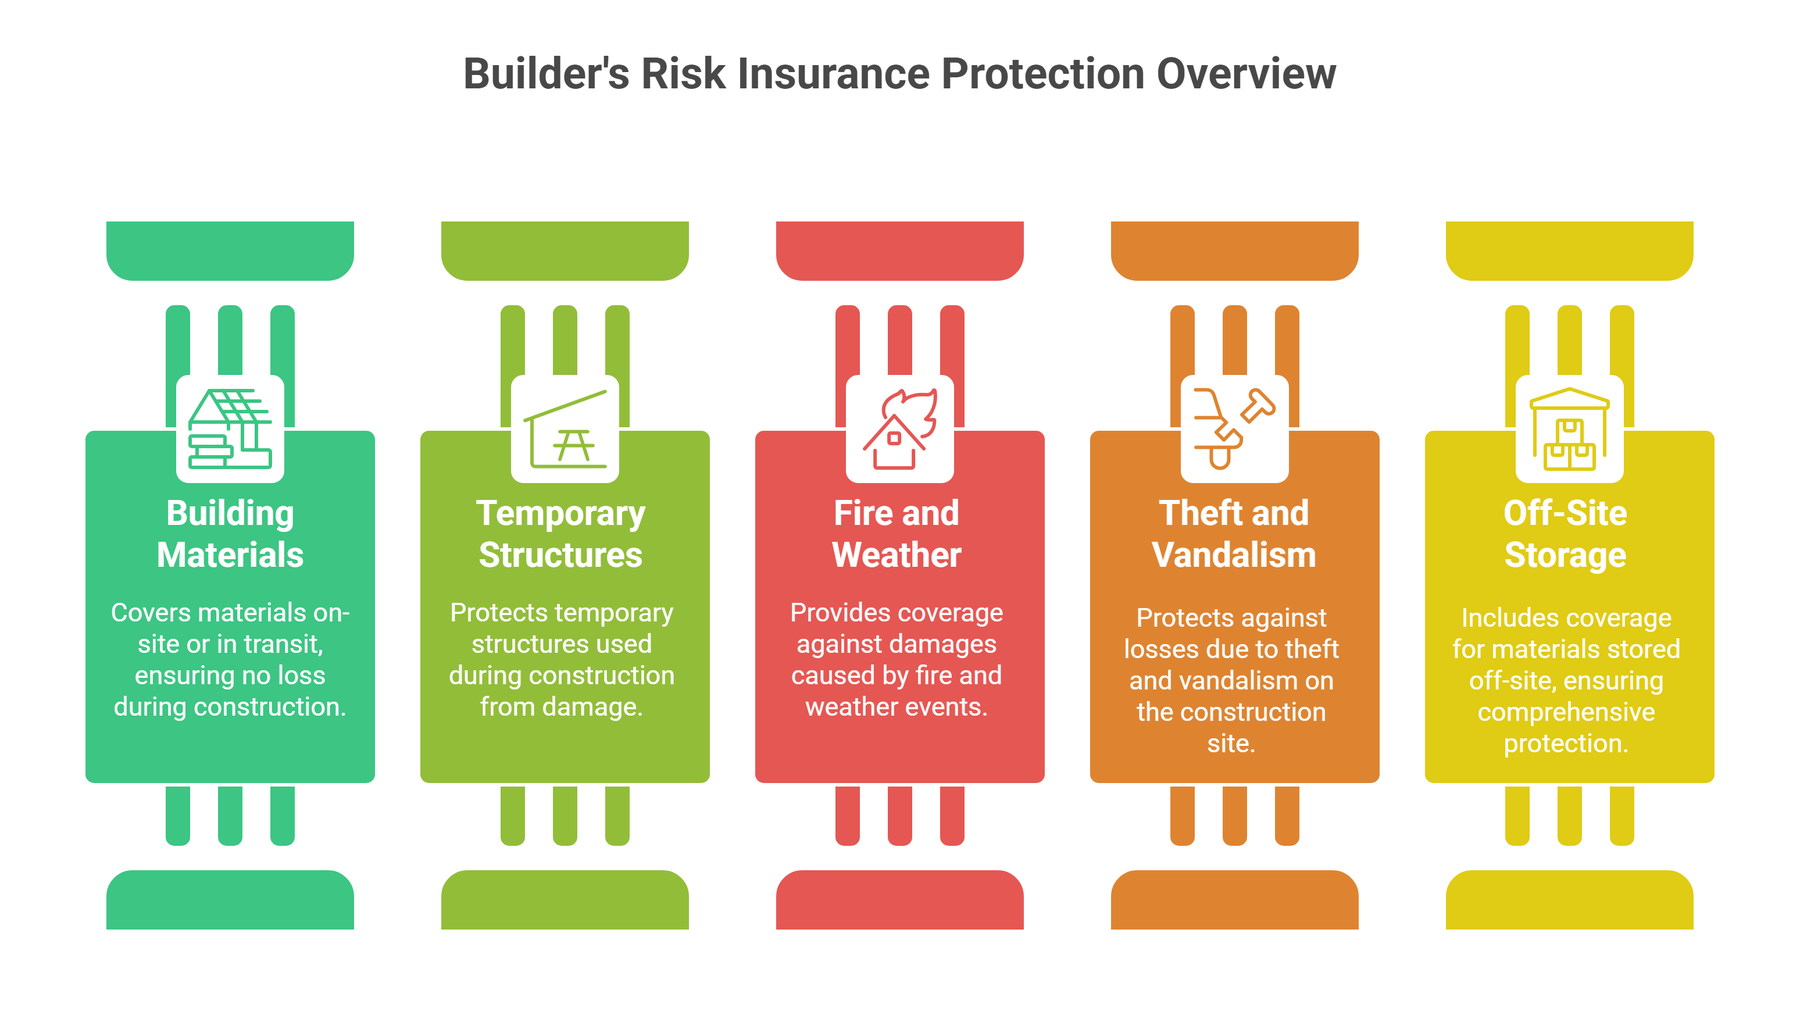
What Builder’s Risk Insurance Typically Doesn’t Cover
Understanding exclusions is just as important as understanding coverage:
- Acts of terrorism
- Normal wear and tear
- Employee theft
- Faulty workmanship, materials, or design
- Earthquakes or floods (unless added)
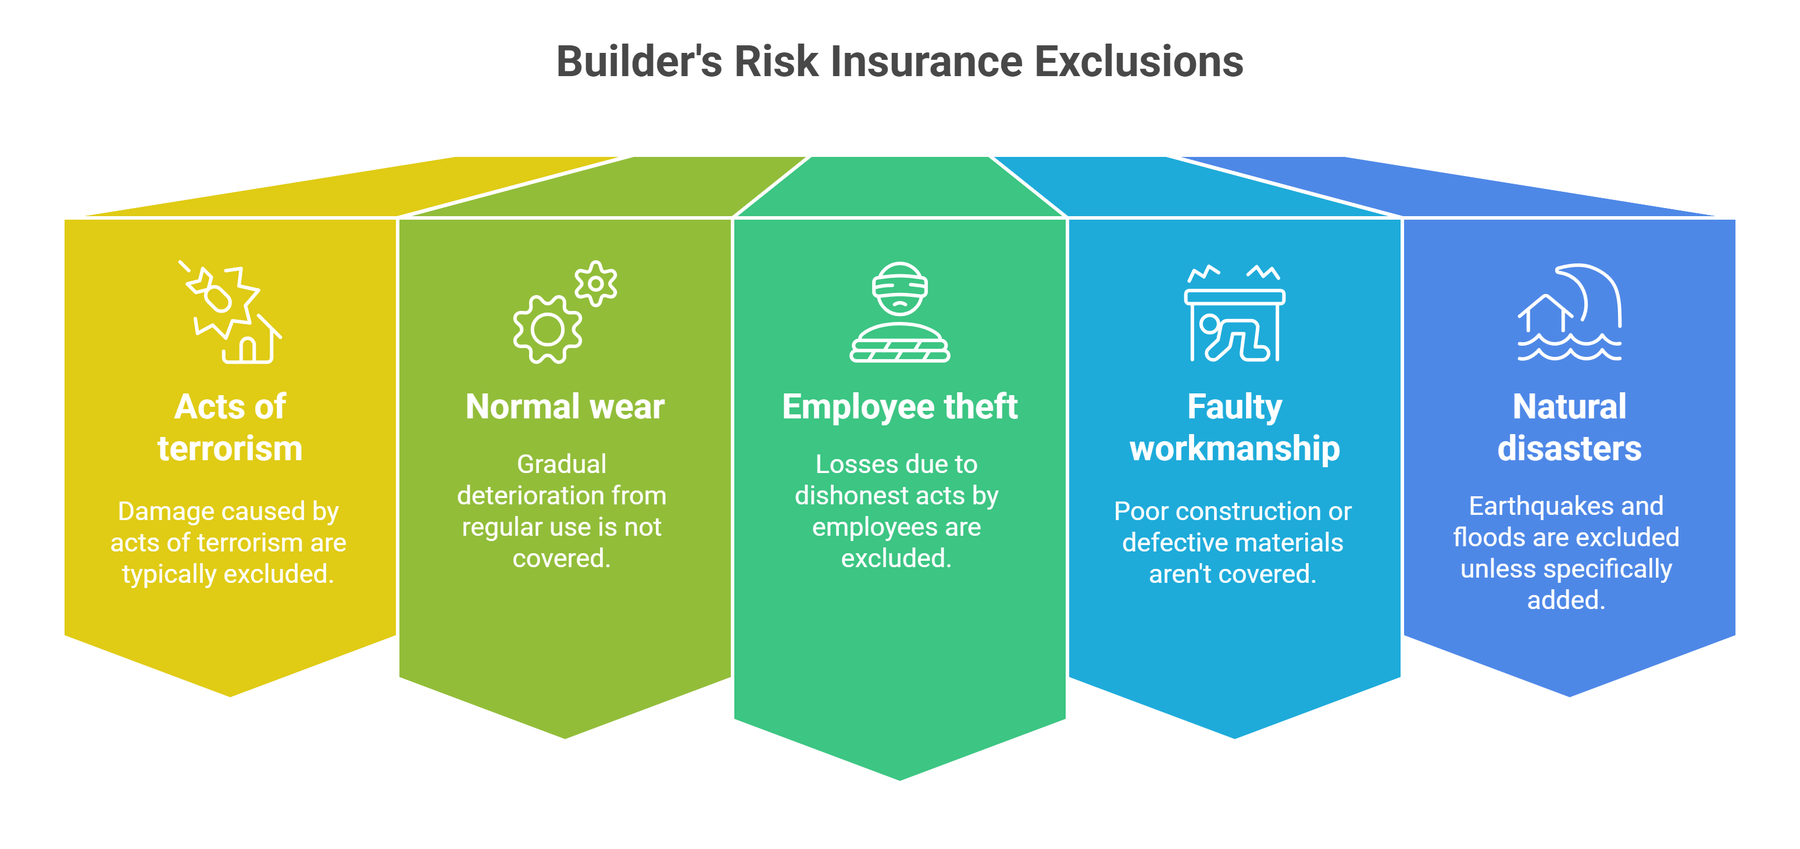
Can It Cover Delays and Soft Costs?
Some builder’s risk policies offer optional endorsements for “soft costs” and delay coverage. These may include:
- Lost rental income
- Interest on construction loans
- Additional permit fees
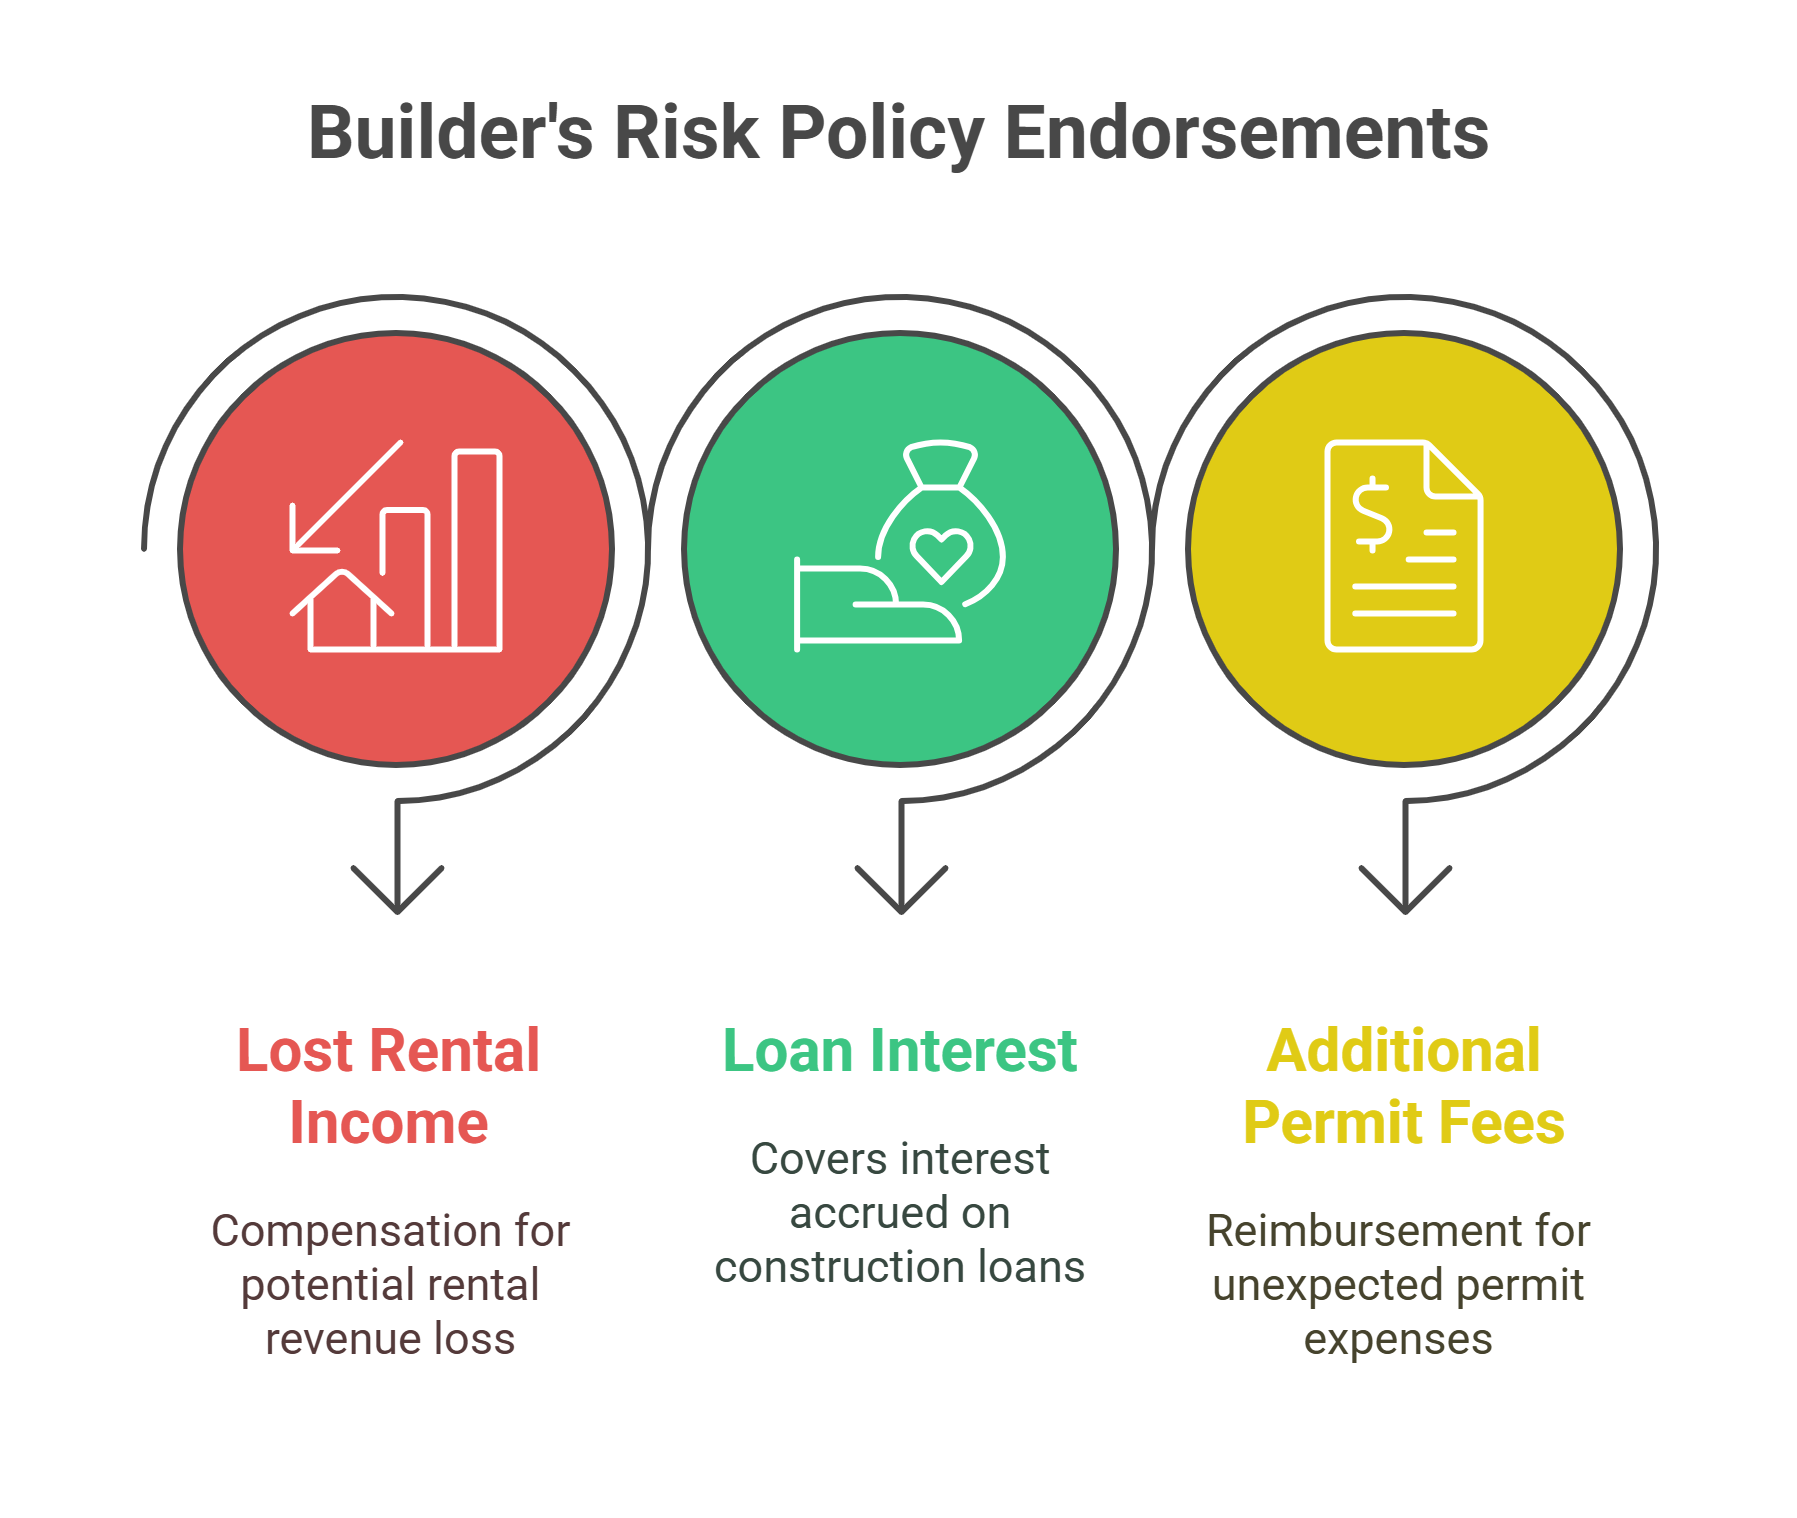
Speak with your agent about including these if you’re concerned about unexpected delays.
How to Choose the Right Builder’s Risk Policy
Not all policies are created equal. Here’s how to choose the right one:
- Assess the scope of your renovation
- Review coverage limits against your project budget
- Compare deductibles and premium rates
- Look for endorsements relevant to San Diego risks (e.g., wildfire, flood)
- Work with a local agent familiar with regional regulations and weather conditions
Summary Table: Key Considerations for Builder’s Risk Insurance
Before purchasing a policy, here are the essential factors to review with your insurance provider:
| Key Factor | What to Review | San Diego Homeowner Tip |
|---|---|---|
| Project Scope & Value | Share detailed plans and cost estimates with your insurer. | Include any custom ADUs, additions, or luxury upgrades common in San Diego neighborhoods. |
| Covered Perils | Ensure fire, theft, wind, and vandalism are included. | Verify wildfire protection if you’re near backcountry areas like Poway or Rancho Santa Fe. |
| Exclusions | Understand what’s not covered, like flood or earthquake damage. | Consider add-ons if you’re in a FEMA floodplain or seismic zone. |
| Policy Timing | Start coverage before demolition and update it once the remodel is complete. | Delays are common, make sure your coverage doesn’t lapse mid-construction. |
| Materials & Equipment | Include stored or in-transit materials and equipment in the policy. | Theft is a risk, especially for coastal or canyon-view homes that are temporarily vacant. |
| Soft Costs | Ask about coverage for permit fees, lost rent, and loan interest if the project is delayed. | Important for homeowners planning to rent out an ADU or short-term vacation space. |
Kaminskiy’s Partnership with Buildertrend Saves You More
At Kaminskiy Design and Remodeling, we make every step of your remodel easier, including the insurance process. Through our partnership with Buildertrend Insurance Services, our clients can access Builder’s Risk Insurance with average savings of 20% on equal or better coverage.2
Why choose Buildertrend Insurance through Kaminskiy?
Unlock better quotes in seven clicks or less
Personalized one-on-one insurance support
Access instant policy documents and binders
Manage coverage and paperwork all in one platform
Liability Insurance and Umbrella Coverage
Even if your contractor is insured, you should maintain robust liability coverage. If a worker gets hurt on your property and the contractor’s policy doesn’t cover it, your insurance may be on the hook.
Permit Compliance and Inspections
Cutting corners on permits can invalidate insurance claims. In San Diego, city inspectors confirm whether your project meets building codes. Noncompliance can void your coverage.
Theft and Vandalism Protections
Remodels are particularly vulnerable to theft, especially when left unattended overnight. Discuss coverage options with your agent for stolen appliances, materials, or tools. Installing cameras or temporary fencing may also lower premiums.
Security Tips:
- Use motion-sensor lighting
- Install temporary fencing or locked storage
- Ask your remodeler about surveillance during off-hours
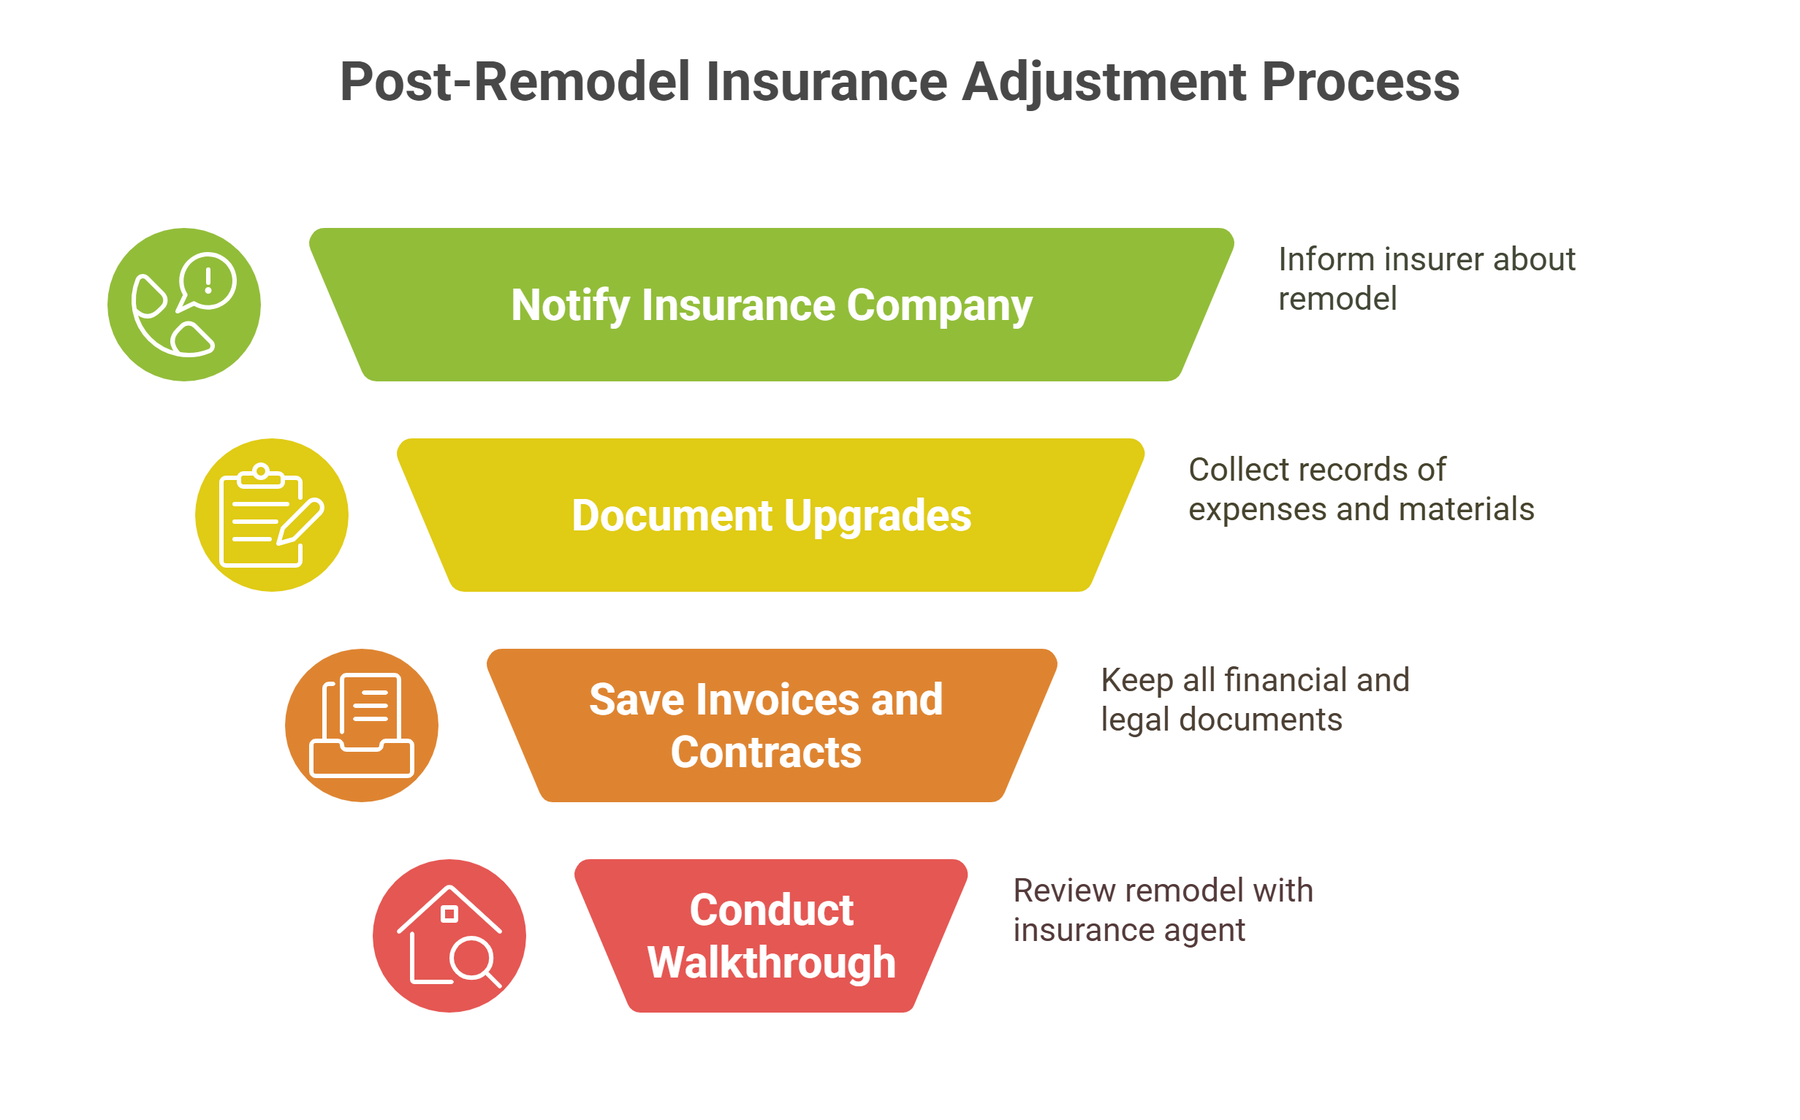
Notify Your Insurance Company
Communicate Changes Early
Let your insurer know about your renovation plans before you begin work. Your project could influence risk factors or premiums. Provide scope, budget, and timeline.
Avoid Claim Denials
Failing to inform your provider can jeopardize coverage if a claim arises during the project. Transparency up front saves major stress later.
Post-Remodel Insurance Adjustments
Update Your Homeowner’s Policy
Once the project wraps up, notify your insurance company. This isn’t just about boosting your coverage, it may even qualify you for discounts, especially if your remodel includes upgraded electrical, plumbing, or fire-resistant features.
Document Every Upgrade
Keep detailed records of expenses, materials used, and before-and-after photos. If you need to file a claim later, this documentation will serve as your best defense.
Do’s and Don’ts:
- Do: Save every invoice and contract
- Don’t: Assume your contractor’s documentation will be enough
Perform a Post-Project Walkthrough with Insurer
Invite your insurance agent for a walkthrough of the finished remodel. This helps ensure coverage is correctly updated and can uncover hidden vulnerabilities or new insurable features.
San Diego-Specific Requirements
Permits and Inspections
Most remodeling work in San Diego requires city permits. The City of San Diego’s Development Services Department outlines the projects that require approval. At Kaminskiy, we handle this process entirely, ensuring your remodel is fully compliant with all relevant regulations.
Verify Contractor Licensing
Only work with licensed contractors registered with the California Contractors State License Board. Licensing is a legal requirement and a safeguard that your contractor meets state-mandated standards.
San Diego-Specific Risks to Insure Against
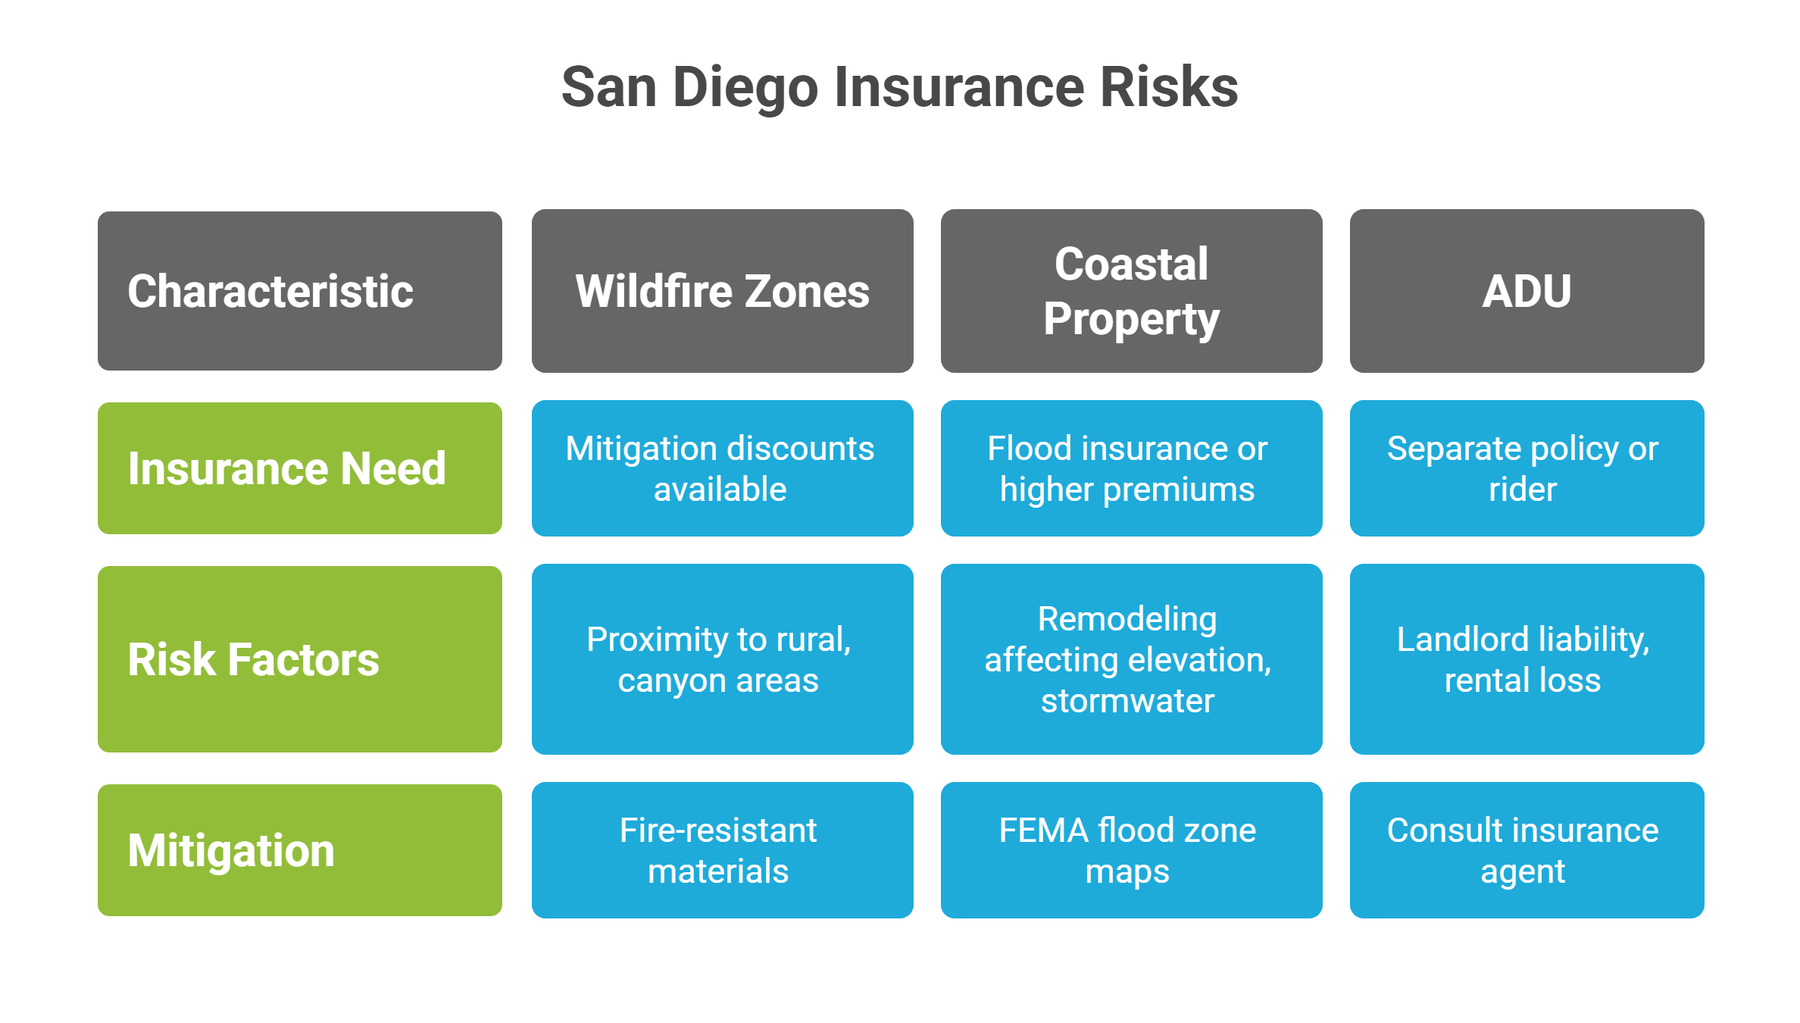
Wildfire Zones
If you added a backyard ADU or expanded your home near fire-prone areas, you may qualify for mitigation discounts, especially if you used fire-resistant materials like fiber-cement siding or Class A roofing.
According to a CalMatters analysis, nearly 3.7 million homes statewide in California are at high or extreme risk for wildfire.3 In San Diego County specifically, many neighborhoods in the backcountry, foothills, and canyon areas face elevated wildfire risk. Take this seriously if you’re near rural or canyon areas, or in communities like Scripps Ranch, Rancho Bernardo, or Ramona.
Coastal Property Flooding
Additions near the coast? You might need flood insurance or higher premiums depending on how the remodel affects elevation and stormwater flow.
Use FEMA’s flood zone maps to check your risk level. Remodeling may change your Base Flood Elevation (BFE).
Building an ADU
ADUs often require a separate policy or a rider. This is especially important if you plan to rent it out. Talk to your agent about landlord liability, rental loss protection, and tenant-related risks.
Working with Insurance Agents
Your best ally during this process is a knowledgeable, local insurance agent. San Diego’s risks, wildfires, earthquakes, coastal flooding, require someone who knows how to navigate local codes and insurance carriers.
Questions to Ask Your Agent:
- Are remodels covered under my current policy?
- Do I need builder’s risk insurance?
- What if I move out temporarily?
- Will my premiums change?
- What endorsements or riders do I need to obtain?
Peace of Mind After the Remodel
At Kaminskiy Design and Remodeling, we don’t just finish the job, we stand behind it. Our full-service design-build process includes a two-year warranty on all our work. If you ever need help providing documentation to your insurer after the project, we’re just a phone call away.
I’ve guided many San Diego homeowners through this process, and I know how overwhelming it can feel. That’s why we created this quick-reference checklist to help you stay organized, protected, and confident from start to finish.
9 Must-Do Insurance Steps Before and After Your San Diego Remodel
Use this quick-reference checklist to ensure your home remodel is fully covered from the start, regardless of the project’s size or scope.
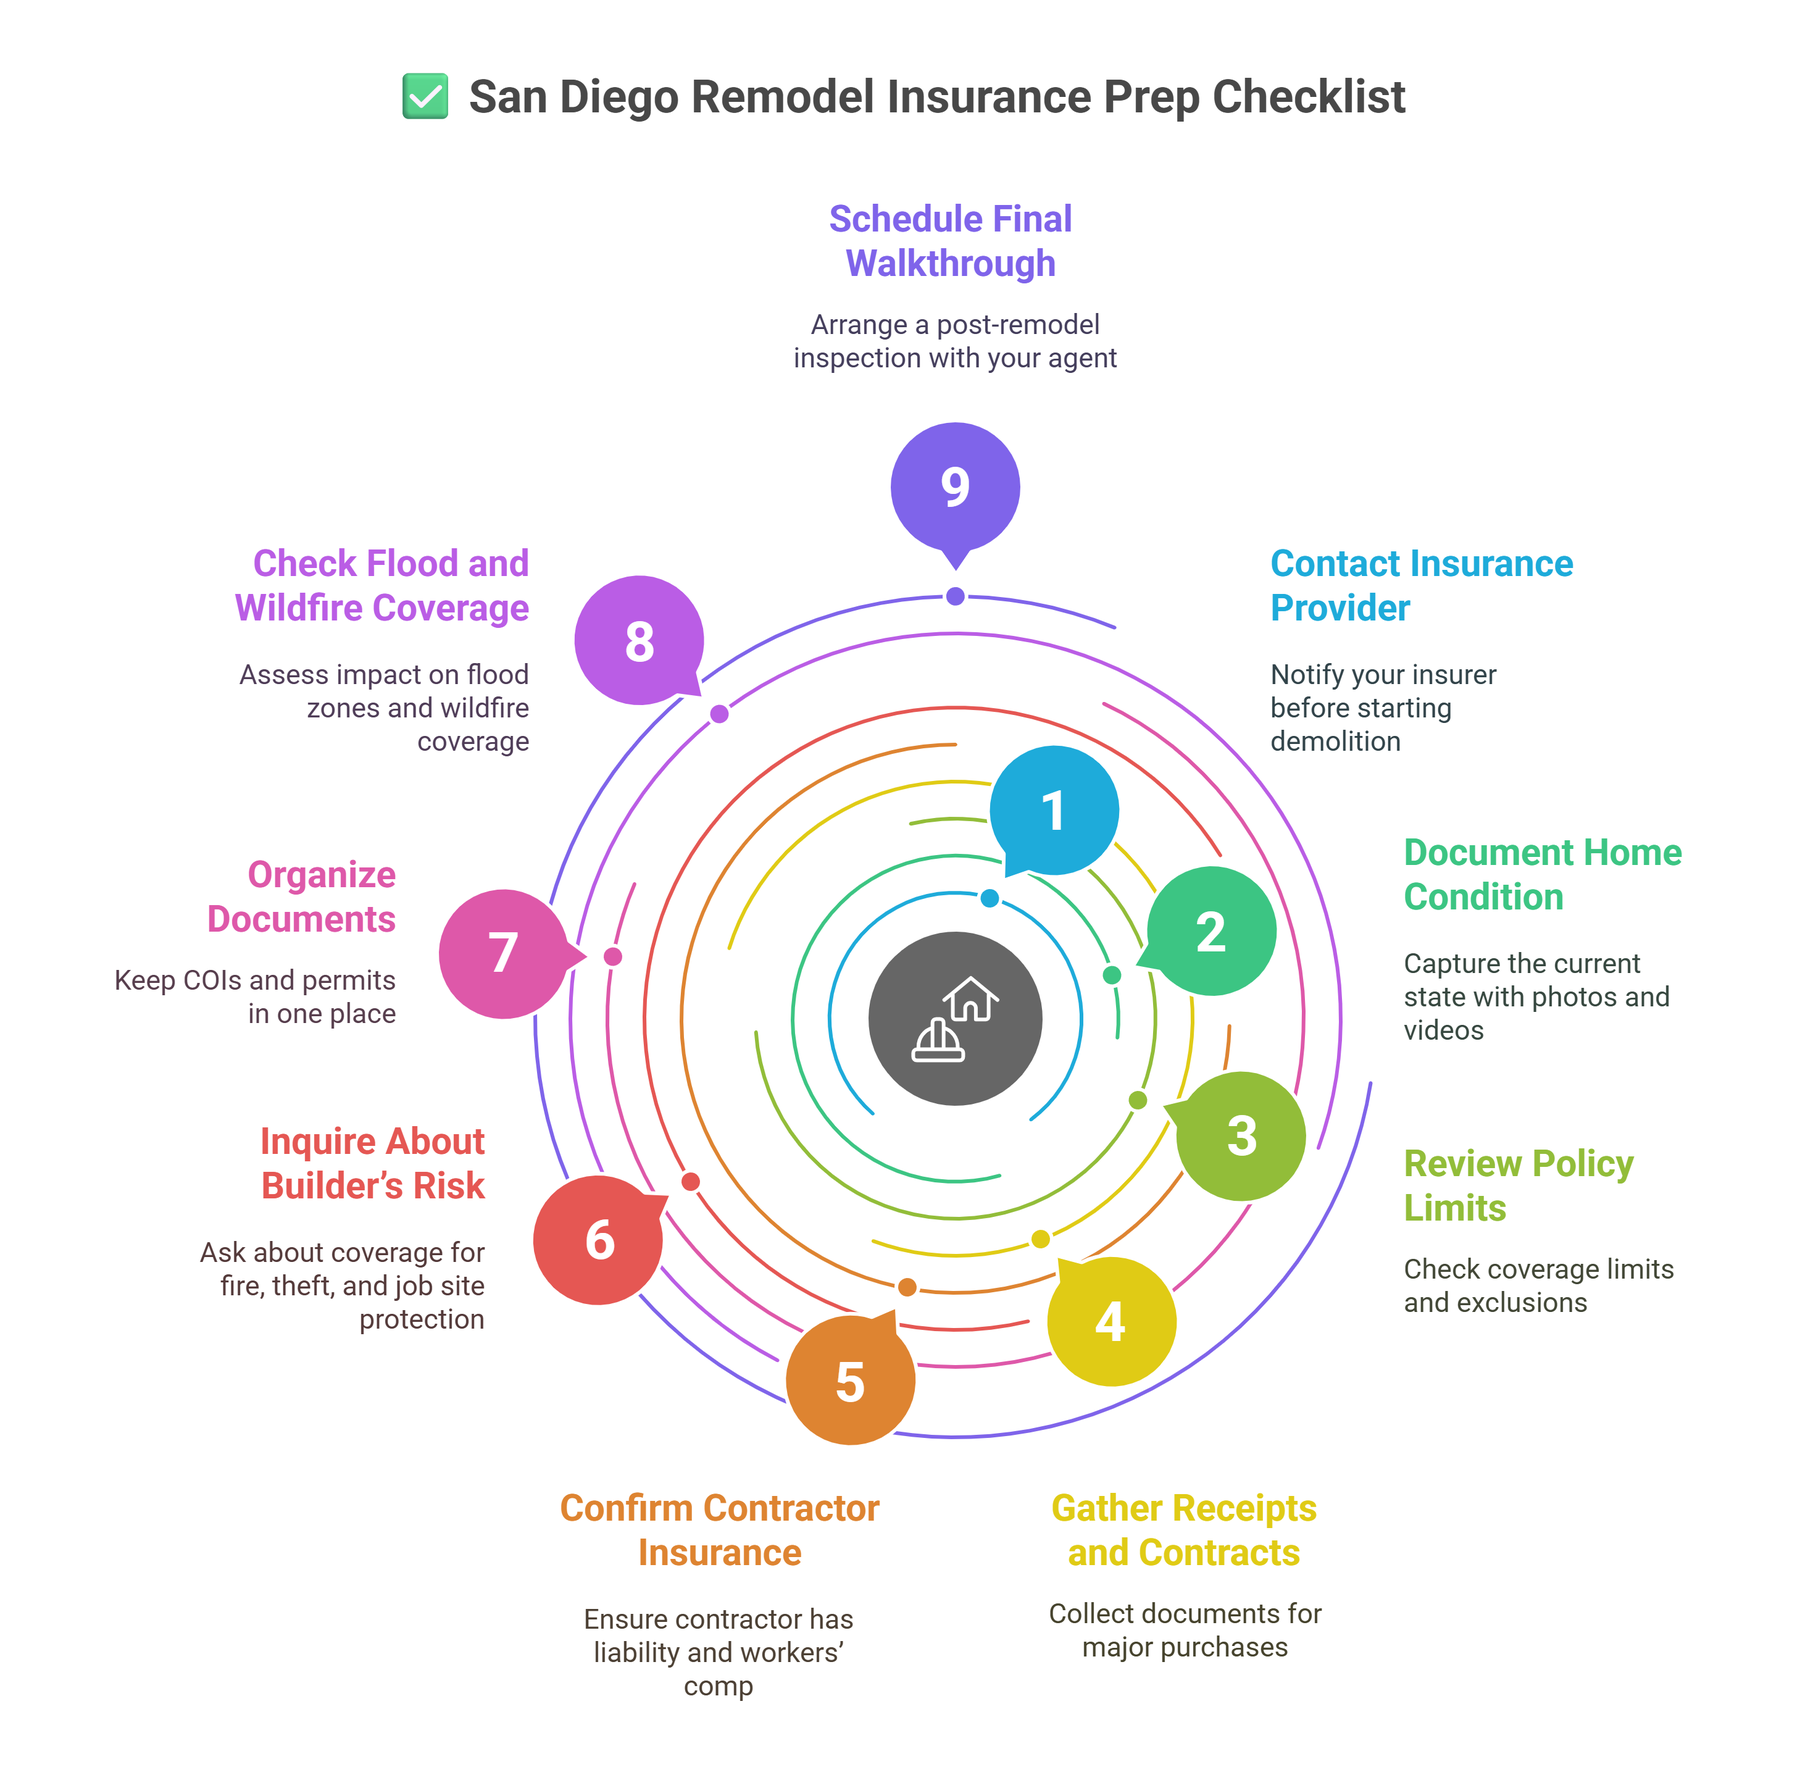
Need help putting this into action? Kaminskiy Design and Remodeling is here to guide you every step of the way, from organizing paperwork to coordinating walkthroughs and documenting your upgrades.
Remodel with Confidence, We’ve Got You Covered
Insurance isn’t the most exciting part of a home remodel, but it’s one of the most important. With the right coverage in place, you can move forward knowing your investment, your family, and your peace of mind are protected.
At Kaminskiy Design and Remodeling, we take that seriously. We’ll handle permits, help you document your upgrades, and back our work with a two-year warranty. You can count on us to be there every step of the way.
Ready to remodel with confidence?
If you’re ready to get started, I’d love for you to give us a call or schedule your free in-home design consultation. Let’s build something beautiful and make sure it’s protected, too.
Schedule Your Free In-Home Consultation
Additional Resources:
- Permits, Approvals & Inspections | City of San Diego Official Website ↩︎
- Builder’s Risk Insurance Explained, Buildertrend ↩︎
- New California fire hazard maps: What homeowners need to know, CalMatters ↩︎
Frequently Asked Questions
Start by assessing your renovation’s full scope and value, including materials, labor, and soft costs like permits or rental income loss. Confirm your policy covers common risks in San Diego, such as wildfire, theft, and coastal weather. Ensure your contractor’s insurance doesn’t leave gaps, and work with a local agent who understands regional construction risks.
Depending on your project, consider endorsements for debris removal, equipment breakdown, materials stored off-site, or loss of use. If your home is near a floodplain or wildfire zone, adding flood or wildfire coverage can be essential. These optional add-ons help reduce out-of-pocket costs and claim denials later.
Yes. An ADU, especially one intended for rental use, may require a separate policy or rider. Discuss landlord liability, rental income protection, and tenant-related coverage with your agent. Even if you’re not renting immediately, securing appropriate coverage now can save you hassle later.
Remodels increase your home’s replacement value. Upgrades like new square footage, premium finishes, or smart systems increase the cost to rebuild, which must be reflected in your policy limits. Request an updated appraisal after the remodel to ensure your coverage meets your home’s new value.
Aside from general construction risks, homeowners in San Diego should factor in wildfire exposure (especially in canyons or foothills), coastal flood risk, and compliance with local permitting regulations. These region-specific risks often require tailored policies or add-ons not included in standard coverage.
Not notifying their insurer before starting work. Failing to update your insurance provider can lead to denied claims or canceled coverage. Always inform them of your project scope and timeline, and request written confirmation of continued coverage.
Ready when you are